AFP-Exam-1인기자격증 시험 덤프자료, AFP-Exam-1높은 통과율 시험공부, AFP-Exam-1최신시험후기, AFP-Exam-1참고덤프, AFP-Exam-1시험대비 최신버전 자료

CSI AFP-Exam-1인증시험패스 하는 동시에 여러분의 인생에는 획기적인 일 발생한것이죠, 사업에서의 상승세는 당연한것입니다. IT업계종사자라면 누구나 이런 자격증을 취득하고싶어하리라고 믿습니다. 많은 분들이 이렇게 좋은 인증시험은 아주 어렵다고 생각합니다. 네 많습니다. 패스할확율은 아주 낮습니다. 노력하지않고야 당연히 불가능하죠.CSI AFP-Exam-1시험은 기초지식 그리고 능숙한 전업지식이 필요요 합니다. 우리Itcertkr는 여러분들한테CSI AFP-Exam-1시험을 쉽게 빨리 패스할 수 있도록 도와주는 사이트입니다. 우리Itcertkr의CSI AFP-Exam-1시험관련자료로 여러분은 짧은시간내에 간단하게 시험을 패스할수 있습니다. 시간도 절약하고 돈도 적게 들이는 이런 제안은 여러분들한테 딱 좋은 해결책이라고 봅니다.
CSI AFP-Exam-1 Exam Syllabus Topics:
| Section |
Weight |
Objectives |
| Estate Planning |
13% |
- Powers of Attorney
- Trust and Beneficiary Planning
- Wills
- Estate Transfer Strategies
|
| Tax Planning |
14% |
- Income Tax Fundamentals
- Tax Deductions and Credits
- Registered Plans
- Tax-Efficient Strategies
|
| Investment Planning |
17% |
- Portfolio Construction
- Investment Products
- Investment Theory
- Asset Allocation
|
| Professional Conduct and Regulatory Compliance |
10% |
- Ethics and Professional Standards
- Regulatory Requirements
- Compliance Responsibilities
|
| Retirement Planning |
17% |
- Retirement Income Strategies
- Pension Plans
- Registered Retirement Savings Plans
- Retirement Needs Analysis
|
| Client Relationship and Practice Management |
6% |
- Communication and Advisory Process
- Practice Management
- Client Discovery
|
| Risk Management and Insurance |
12% |
- Life Insurance
- Risk Assessment
- Disability and Health Insurance
- Risk Transfer Strategies
|
| Asset and Liability Management |
11% |
- Debt Management
- Budgeting
- Personal Balance Sheet Analysis
- Cash Flow Management
|
>> CSI AFP-Exam-1인기자격증 시험 덤프자료 <<
AFP-Exam-1인기자격증 시험 덤프자료 덤프 ----- IT전문가의 노하우로 만들어진 시험자료
CSI AFP-Exam-1덤프의 유효성을 보장해드릴수 있도록 저희 기술팀은 오랜시간동안CSI AFP-Exam-1시험에 대하여 분석하고 연구해 왔습니다. CSI AFP-Exam-1 덤프를 한번 믿고CSI AFP-Exam-1시험에 두려움없이 맞서보세요. 만족할수 있는 좋은 성적을 얻게 될것입니다.
최신 Canadian Securities Course AFP-Exam-1 무료샘플문제 (Q60-Q65):
질문 # 60
A financial planner recently started her new role at the bank and decided to create a checklist when meeting with prospects. She wanted to include one item on the checklist that would allow her to understand her clients' tolerance for risk. What information should she add, that will help her achieve this objective?
- A. Tax returns.
- B. Previous financial plan.
- C. Life insurance policy.
- D. Qualitative questionnaire.
정답:D
설명:
Risk tolerance is measured through qualitative discovery, not through tax records or product documents. A properly designed questionnaire captures how the client thinks and behaves when markets decline, how much volatility is acceptable, whether losses create anxiety, and how the client prioritizes safety versus growth. Tax returns may reveal income and deductions, but they do not establish willingness to accept investment risk. A life insurance policy is relevant to risk management, not market-risk tolerance. A previous financial plan may provide useful background, but it may be outdated and still requires current confirmation. The questionnaire is only one part of the process; the planner should also assess risk capacity using objective facts such as time horizon, liquidity, income stability, debt level, and goal flexibility. For the checklist item requested, however, qualitative questionnaire is the correct answer. Study Guide focus: risk profiling, qualitative discovery, behavioural finance, KYC, and suitability. That behavioural evidence is then reconciled with objective capacity before an investment recommendation is made.
질문 # 61
Justis, age 62, and his wife Jen, age 58, are meeting with their financial planner, Luke. They are both planning to retire by age 65. Their goals are to minimize debt and reduce taxes. The couple's financial situation is outlined below.
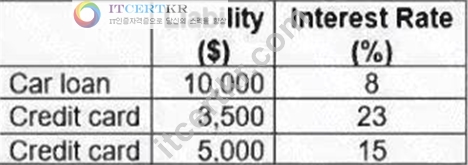
Justis' annual income is $25,000. He has a $15,000 RRSP, $30,000 single non-registered account and a
$25,000 TFSA. Jen's annual income is $60,000, and she has a $150,000 RRSP, $50,000 single non-registered account and a $20,000 TFSA.
Jen's marginal tax rate is 35%, and Justis' is 25%. Assuming all investments are making interest income of
10%, what would be the most appropriate strategy for Luke to recommend for the couple?
- A. Use Justis's non-registered funds to pay off all liabilities.
- B. Use Jen's RRSP to pay all liabilities.
- C. Use Jen's non-registered funds to pay all liabilities.
- D. Use Justis's RRSP to pay off all liabilities.
정답:C
설명:
Luke should recommend using Jen's non-registered funds because that option clears the liabilities without triggering registered-plan withdrawal income. The debts total $18,500 and include expensive consumer borrowing: credit cards at 23% and 15%, plus a car loan at 8%. The couple's taxable investments earn 10% interest before tax, so Jen's after-tax return is approximately 6.5% at a 35% marginal rate. Paying the credit cards is equivalent to earning a risk-free after-tax return equal to the interest avoided, which is materially better than leaving the money invested. Using either spouse's RRSP would create taxable income and permanently reduce retirement capital. Using Justis's non-registered funds is less effective because his lower tax rate makes his after-tax investment return higher than Jen's, so Jen's taxable account is the better source.
Study Guide focus: debt repayment priority, after-tax returns, registered versus non-registered withdrawals, and household cash-flow planning. The recommendation also preserves retirement accounts for the couple's age-65 objective while eliminating the highest-cost liabilities first.
질문 # 62
A financial planner, Rachel, is preparing to recommend a discretionary portfolio manager to her client. The portfolio manager is owned by Rachel's former employer, and Rachel receives no referral fee. However, the former employer regularly sends new clients to Rachel's practice. What should Rachel do before making the recommendation?
- A. Disclose the relationship and the potential conflict before the client decides.
- B. Proceed because no monetary referral fee is paid.
- C. Recommend the manager only if the client signs a risk acknowledgement form.
- D. Avoid discussing the portfolio manager and let the client find one independently.
정답:A
설명:
Course-guide reasoning starts with the conflict, not the commission. A conflict exists when a planner's judgment could reasonably be influenced by a relationship, incentive, expectation, or business arrangement.
Rachel's former employer may not pay her directly, but the reciprocal referral pattern creates a benefit that could affect, or appear to affect, objectivity. Professional conduct requires timely disclosure in plain language before the client acts on the recommendation. Disclosure should explain the relationship, the nature of the benefit, and how Rachel will continue to act in the client's interest. Option A is too narrow because conflicts are not limited to cash compensation. Option C is unnecessarily defensive; a conflicted recommendation may still be made if it is suitable and properly managed. Option D does not cure the conflict because acknowledging investment risk is different from understanding adviser bias. The defensible action is written disclosure, suitability analysis, and clear documentation. References/topics: conflicts of interest, disclosure obligations, objectivity, professional conduct.
질문 # 63
Mary, an accredited financial planner, recently met with clients Michael and Radha. They are high- net-worth clients who are in their mid-40s. Michael is a heavy equipment operator at a local oil field, and Radha is a homemaker. They are ready to retire in 10 years and very excited to start planning for the next chapter in their lives. Mary explained her planning process, her accreditation, and her remuneration. When Mary presented the client agreement letter, both clients were surprised. They said they did not know why they would sign a letter to get advice on their own finances. How should Mary answer their question?
- A. The client agreement letter sets expectation for the partnership between, the client, the financial planner and their partners.
- B. The client agreement letter is a non-legally binding contract that outlines the business relationship between the clients and the financial institution.
- C. The client agreement outlines the specific financial planning strategies that will be implemented to help both Michael and Radha achieve their financial goals.
- D. The client agreement letter outlines the overall investment strategy that is being recommended by Mary to Michael and Radha.
정답:A
설명:
Mary should explain that the client agreement letter is the engagement document for the advisory relationship.
It confirms what services will be provided, the scope of planning, the roles and responsibilities of the clients and planner, how the planner is compensated, and any limitations or business arrangements that matter to the relationship. It is not the investment strategy itself; that comes after discovery, analysis, and recommendations. It is also not merely an informal or irrelevant bank form. A well-written engagement letter protects the clients because it tells them what they can expect, what information they must provide, and how decisions will be documented. For high-net-worth clients, clarity is even more important because multiple planning areas, specialists, and implementation steps may be involved. Mary should position the letter as a professional standard, not as a barrier to advice. Study Guide focus: engagement letters, financial planning process, client expectations, disclosure, and practice management.
질문 # 64
Carla, a financial planner, is meeting with a long-standing client, Jonathan. Jonathan informs Carla that he is upset and disappointed with the negative returns experienced with his investment portfolio. After acknowledging Jonathan's concerns, what should Carla's first step be in addressing his complaint?
- A. Offer alternative investment options in line with Jonathan's risk tolerance.
- B. Revisit Jonathan's goals, objectives and risk tolerance with him.
- C. Remind Jonathan about the risks associated with investing, as well as the possible volatility and impact on investment returns.
- D. Remind Jonathan that investing is a long-term process and losses will likely be recovered.
정답:B
설명:
After acknowledging Jonathan's concern, Carla should revisit his goals, objectives, and risk tolerance. A complaint about negative returns may indicate normal market volatility, unsuitable risk exposure, changed circumstances, or misunderstanding of the investment plan. The planner should not immediately recommend replacement investments before confirming whether the current portfolio still fits the client's KYC profile.
Simply reminding Jonathan that investing is long term may sound dismissive and does not address suitability.
Repeating that investments involve volatility may be accurate but incomplete. The first professional step is to re-open the planning conversation, confirm objectives, time horizon, liquidity needs, risk tolerance, risk capacity, and expectations, then determine whether any portfolio change or complaint process is required.
AFP practice emphasizes review and documentation when a client expresses dissatisfaction with investment outcomes. Study Guide focus: client review meetings, complaints, risk tolerance, portfolio suitability, and relationship management. The review may show that no product change is required, but that conclusion must be supported by updated facts.
질문 # 65
......
Itcertkr의CSI AFP-Exam-1덤프로CSI AFP-Exam-1시험공부를 하여 시험에서 떨어지는 경우 덤프비용전액을 환불해드릴만큼 저희 덤프는 높은 적중율을 자랑하고 있습니다. 주문번호와 불합격성적표를 메일로 보내오시면 바로 환불가능합니다. 환불해드린후에는 무료업데이트 서비스가 종료됩니다. CSI AFP-Exam-1 시험을 우려없이 패스하고 싶은 분은 저희 사이트를 찾아주세요.
AFP-Exam-1높은 통과율 시험공부: https://www.itcertkr.com/AFP-Exam-1_exam.html
- 시험대비 AFP-Exam-1인기자격증 시험 덤프자료 최신 덤프공부 🌁 [ www.exampassdump.com ]은( AFP-Exam-1 )무료 다운로드를 받을 수 있는 최고의 사이트입니다AFP-Exam-1유효한 최신버전 덤프
- AFP-Exam-1덤프샘플문제 다운 🤫 AFP-Exam-1시험패스 가능 공부자료 👯 AFP-Exam-1시험대비 덤프 최신자료 🕌 ➤ www.itdumpskr.com ⮘을(를) 열고✔ AFP-Exam-1 ️✔️를 입력하고 무료 다운로드를 받으십시오AFP-Exam-1높은 통과율 덤프공부문제
- AFP-Exam-1인기자격증 시험 덤프자료 덤프는 Applied Financial Planning Certification Exam 1 (AFP) 시험의 높은 적중율을 자랑 🔗 검색만 하면➥ www.passtip.net 🡄에서【 AFP-Exam-1 】무료 다운로드AFP-Exam-1높은 통과율 덤프공부문제
- 최신버전 AFP-Exam-1인기자격증 시험 덤프자료 시험대비 덤프공부 🚗 ➤ www.itdumpskr.com ⮘을(를) 열고“ AFP-Exam-1 ”를 입력하고 무료 다운로드를 받으십시오AFP-Exam-1합격보장 가능 공부
- AFP-Exam-1 {Keyword1 }100% 합격 보장 가능한 덤프자료 💏 [ AFP-Exam-1 ]를 무료로 다운로드하려면「 www.itdumpskr.com 」웹사이트를 입력하세요AFP-Exam-1덤프샘플문제 체험
- AFP-Exam-1적중율 높은 시험대비덤프 ⏮ AFP-Exam-1높은 통과율 시험공부 🛷 AFP-Exam-1시험대비 인증덤프자료 🐎 「 www.itdumpskr.com 」의 무료 다운로드▶ AFP-Exam-1 ◀페이지가 지금 열립니다AFP-Exam-1시험대비 인증덤프자료
- AFP-Exam-1 {Keyword1 }100% 합격 보장 가능한 덤프자료 🤮 ▛ www.koreadumps.com ▟에서 검색만 하면➥ AFP-Exam-1 🡄를 무료로 다운로드할 수 있습니다AFP-Exam-1 PDF
- 최신버전 AFP-Exam-1인기자격증 시험 덤프자료 시험대비 덤프공부 🗨 ✔ www.itdumpskr.com ️✔️을 통해 쉽게➤ AFP-Exam-1 ⮘무료 다운로드 받기AFP-Exam-1최고품질 시험대비자료
- AFP-Exam-1덤프샘플문제 체험 🛹 AFP-Exam-1높은 통과율 덤프공부문제 🕜 AFP-Exam-1유효한 최신버전 덤프 🥫 [ www.dumptop.com ]에서☀ AFP-Exam-1 ️☀️를 검색하고 무료 다운로드 받기AFP-Exam-1덤프샘플문제 체험
- AFP-Exam-1최신 덤프데모 다운로드 🏡 AFP-Exam-1덤프문제은행 🐲 AFP-Exam-1시험패스 가능한 인증공부자료 🚀 검색만 하면➡ www.itdumpskr.com ️⬅️에서⇛ AFP-Exam-1 ⇚무료 다운로드AFP-Exam-1높은 통과율 시험공부
- AFP-Exam-1적중율 높은 시험대비덤프 📦 AFP-Exam-1덤프샘플문제 다운 📼 AFP-Exam-1높은 통과율 덤프공부문제 ➡️ { www.koreadumps.com }에서 검색만 하면▛ AFP-Exam-1 ▟를 무료로 다운로드할 수 있습니다AFP-Exam-1유효한 최신버전 덤프
-
www.stes.tyc.edu.tw, www.stes.tyc.edu.tw, www.stes.tyc.edu.tw, www.stes.tyc.edu.tw, www.stes.tyc.edu.tw, www.stes.tyc.edu.tw, www.stes.tyc.edu.tw, www.stes.tyc.edu.tw, www.stes.tyc.edu.tw, www.stes.tyc.edu.tw, Disposable vapes


 icons at the top
right corner of the subsection.